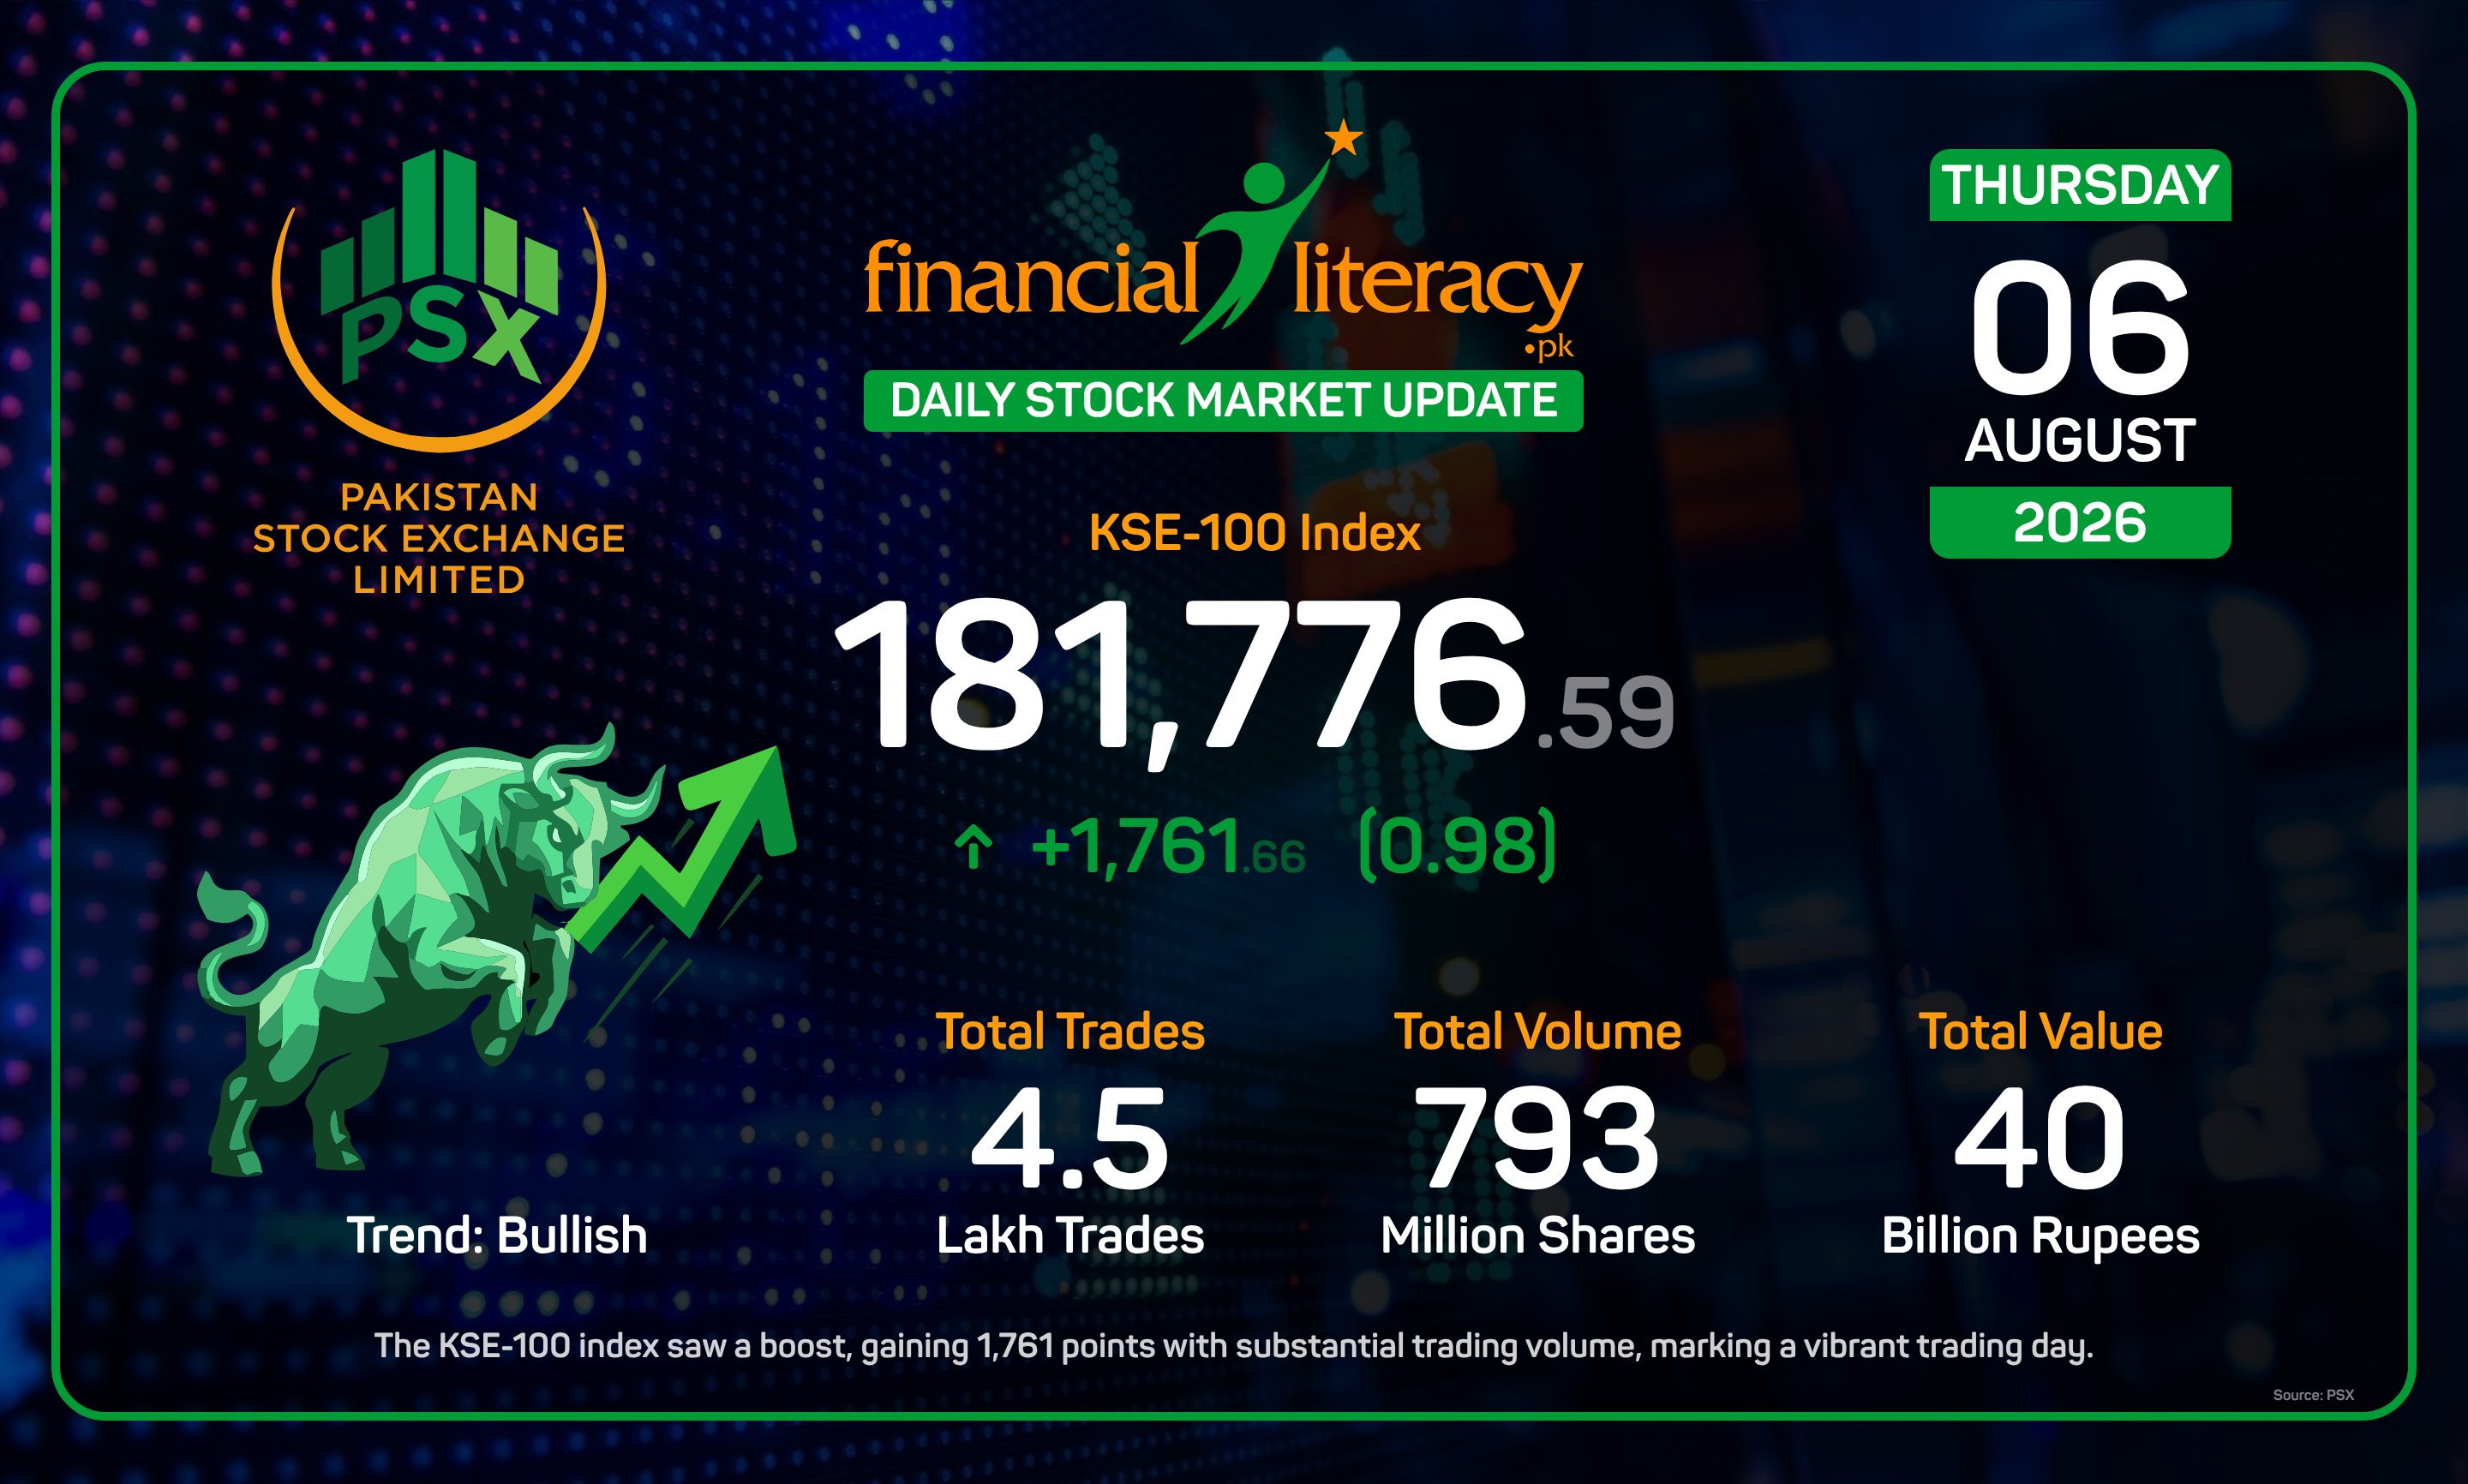
The Pakistan Stock Exchange (PSX) capped off the final week of July 2026 on a resilient note, staging a dramatic recovery driven by easing Middle East geopolitical friction, a drop in international crude oil prices, and monetary policy clarity from the State Bank of Pakistan (SBP).
Having suffered severe selling pressure earlier in the month due to escalating US-Iran hostilities, the benchmark KSE-100 Index reclaimed substantial ground during the week of July 27 to July 31, 2026, fluctuating in the 175,000–178,000 range and ending the month on a positive momentum.
Key Market Highlights
- Benchmark Closing: KSE-100 Index settled near 176,094 points to close out the week on July 31.
- Weekly High/Low Range: Touched an intraday high of 178,588 points (Monday) and an intraday low of 175,153 points.
- Primary Drivers: A pause in US-Iran military strikes, a ~6% plummet in global Brent crude oil prices, and SBP maintaining the policy rate at 11.5%.
- Top Performing Sectors: Commercial Banks, Cement, Oil & Gas Exploration, and Power Generation.
Daily Market Trajectory & Major Drivers
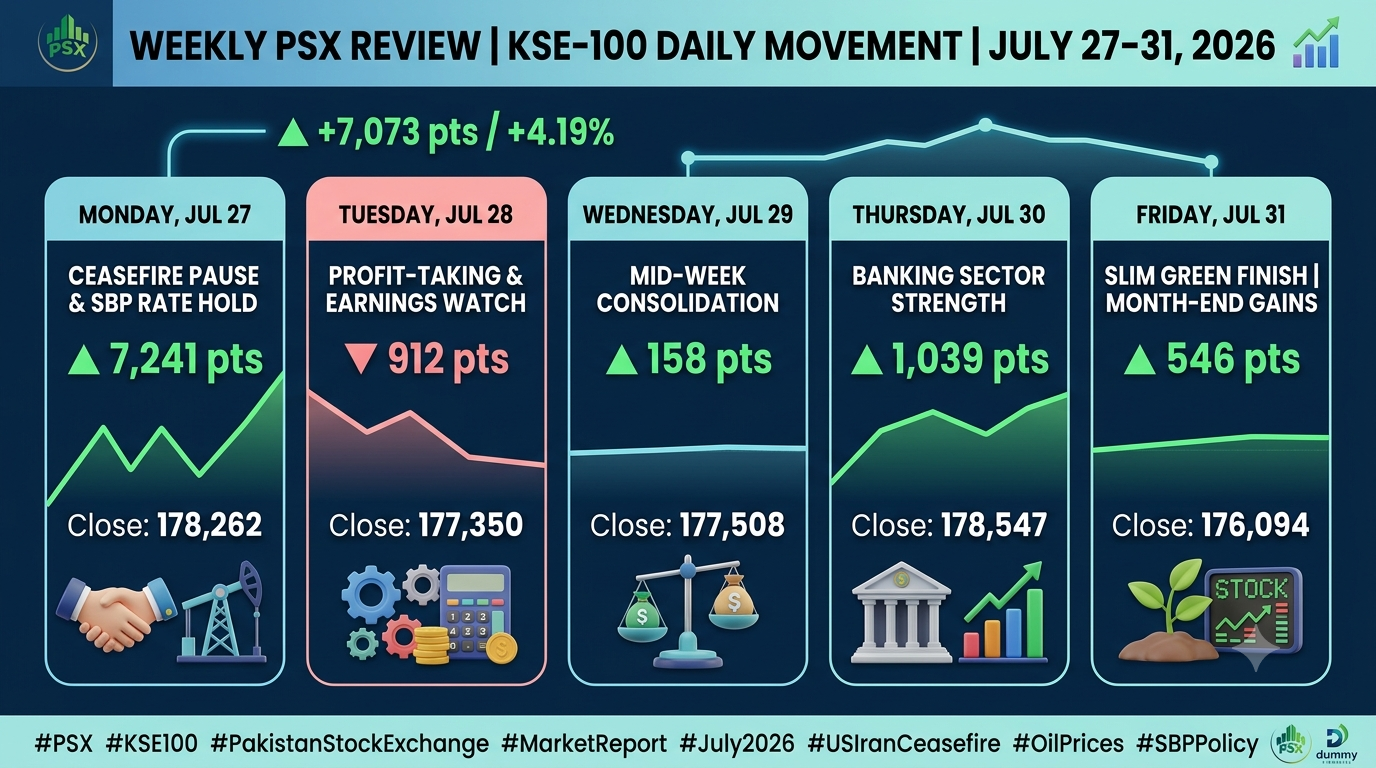
[Mon, Jul 27] --- Strong Surge (+7,241 pts) on US-Iran ceasefire pause & SBP rate hold
      │
[Tue-Thu]     --- Mid-week consolidation, profit-taking & corporate earnings tracking
      │
[Fri, Jul 31] --- Slim Green Finish (+546 pts) to wrap up the month
Monday, July 27: Massive Bullish Surge (+7,241 pts)
The week opened with historic buying enthusiasm following a weekend pause in military actions between the US and Iran.
- The Catalysts: Reports of a holding truce and potential ceasefire negotiations in the Strait of Hormuz caused international Brent crude to plummet over 5–6% (falling back below $90/barrel).
- Market Action: The KSE-100 Index soared 7,241.13 points (+4.23%) to close at 178,262.34. Trading volumes exploded to over 1.03 billion shares. Confidence was further bolstered when the SBP announced its decision to maintain the policy rate unchanged at 11.5%.
Tuesday – Thursday (July 28–30): Consolidation & Corporate Earnings
Following Monday’s historic run, the market entered a period of healthy profit-taking and consolidation as investors digested corporate financial results.
- Geopolitical Watch: Market participants monitored news regarding mediation efforts (supported by regional players including Oman and Pakistan) aimed at keeping shipping lanes open.
- Domestic Focus: Investors turned their focus to earnings season releases from heavyweights including United Bank Limited (UBL), Bestway Cement, Nestlé Pakistan, and PTCL.
Friday, July 31: Slim Green Finish (+546 pts)
The final trading session of July saw selective buying across index heavyweights, helping the market lock in gains before the weekend.
- Market Action: The benchmark index gained 546.13 points (+0.31%), closing at 176,094.11 points.
- Key Drivers: Commercial banks, textile, and cement stocks led the closing rally, offset slightly by mild selling in the energy exploration sector as crude oil prices stabilized.
Core Factors Shaping the Week
| Factor | Nature | Market Impact |
| US-Iran Ceasefire Pause | International | High Positive: Reduced global supply disruption risks and lowered energy import fears for Pakistan. |
| Crude Oil Pullback | International | High Positive: Brent crude falling from $100+ down to ~$88–$90/bbl eased inflation expectations. |
| SBP Monetary Policy | Local | Positive Neutral: Keeping interest rates steady at 11.5% provided macroeconomic stability. |
| FY26 Corporate Results | Local | Mixed / Sectoral: Dividend payouts from banking and cement heavyweights attracted institutional buying. |
Market Outlook
Heading into August 2026, market sentiment remains cautiously optimistic. While the de-escalation of the US-Iran conflict has provided temporary relief to global markets and lowered Pakistan’s import bill pressure, equity performance will continue to hinges on:
- Stability in the Middle East and unimpeded transit through the Strait of Hormuz.
- Continuation of strong corporate earning payouts throughout the ongoing reporting season.
- Inflation trajectories and foreign portfolio flows into emerging equities.
Sector-Wise PSX Performance Review (July 27 – 31, 2026)
Weekly Overview Summary
| Sector | Weekly Trend | Major Drivers & Catalysts | Key Notable Stocks |
|---|---|---|---|
| Commercial Banks | 🟩 Bullish | SBP rate hold at 11.5%; strong HY26 corporate earnings and payouts. | UBL, MCB, MEBL, HBL |
| Energy (E&P & Power) | 🟨 Volatile / Mixed | Global crude oil drop (~6%) following US-Iran ceasefire reports; circular debt updates. | OGDCL, PPL, POL, HUBCO |
| Cement | 🟩 Bullish | Lower international coal and freight costs; strong full-year dividend announcements. | Bestway Cement, Lucky Cement, DGKC |
1. Commercial Banking Sector 🏛️
- Performance Trend: Strong Gain / Market Leader
- Key Sector Drivers:
- Monetary Policy Continuity: The State Bank of Pakistan’s (SBP) decision to maintain the policy rate at 11.5% sustained strong Net Interest Margins (NIMs) for commercial banks.
- Earnings & Dividend Announcements: Heavyweight financial results—such as United Bank Limited (UBL) declaring a 160% (PKR 16/share) interim dividend for HY26—triggered aggressive institutional buying.
- Top Movers: UBL, Meezan Bank (MEBL), MCB Bank, and Habib Bank (HBL).
2. Energy Sector (E&P, Refineries, & Power) ⚡
- Performance Trend: Volatile Consolidation
- Key Sector Drivers:
- Crude Oil Pullback: The primary factor impacting Exploration & Production (E&P) companies was the rapid drop in global Brent crude oil prices (falling ~6% to the $88–$90/barrel range) after US-Iran truce news emerged over the weekend.
- Earnings Impact: Lower international oil prices reduced profit margin projections for upstream players (OGDCL, PPL, POL), resulting in selective profit-taking mid-week.
- Power Generation Relief: Downstream power and manufacturing companies saw relief due to expected stabilization in fuel import costs.
- Top Movers: OGDCL, Pakistan Petroleum Limited (PPL), Pakistan Oilfields (POL), and HUBCO.
3. Cement Sector 🏗️
- Performance Trend: Steady Upward Momentum
- Key Sector Drivers:
- Lower Input Costs: Reduced global energy prices and easing maritime shipping tensions in the Middle East led to lower international coal and freight rates, directly boosting margin prospects for cement manufacturers.
- Annual Financial Results: Robust full-year financial disclosures provided positive momentum. Bestway Cement’s FY26 financial release—highlighting a 100% final dividend—helped lift investor confidence across the entire sector.
- Top Movers: Bestway Cement, Lucky Cement, and D.G. Khan Cement (DGKC).