Market Trajectory and Rollercoaster Sessions
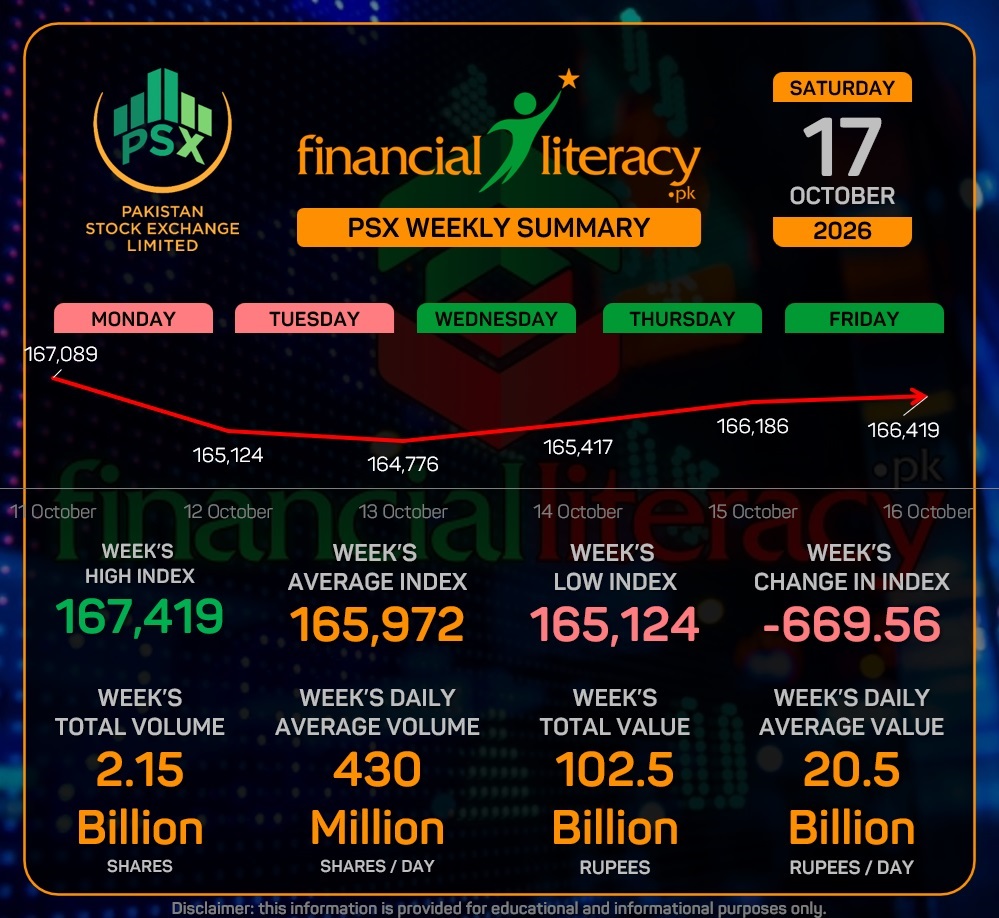
The week got off to a bruising start on Monday, October 12, when heavy institutional selling and broad-based correction shaved off 1,964.86 points (-1.18%) in a single session to drop the index to a weekly low of 165,124.41. While subsequent sessions saw intermittent buying interest—highlighted by mid-week gains on Wednesday (+641.06 points) and Thursday (+768.66 points)—the momentum lacked the depth required to break past resistance barriers. A modest recovery on Friday (+233.55 points) failed to pull the weekly ledger into green territory.
PSX Weekly Summary (12 Oct – 16 Oct 2026)
| Field | Value / Metric |
| Week’s High Index | 167,419.72 |
| Week’s Average Index | 165,972.10 |
| Week’s Low Index | 165,124.41 |
| Week’s Change in Index | -669.56 points (-0.40%) |
| Week’s Total Volume | ~2.15 Billion shares |
| Week’s Daily Average Volume | ~430 Million shares/day |
| Week’s Total Value | ~Rs. 102.5 Billion |
| Week’s Daily Average Value | ~Rs. 20.5 Billion/day |
Daily Market Breakdown
- Monday (12 October): Index opened under heavy selling pressure, plunging by 1,964.86 points (-1.18%) to close at 165,124.41.
- Tuesday to Thursday (13–15 October): The market experienced intermittent recovery and range-bound sessions, making up ground across consecutive positive sessions.
- Friday (16 October): The KSE-100 index extended its late-week winning streak, adding 233.55 points (+0.14%) to close the week out at 166,419.72.
Key Drivers and Factors Stalling Recovery
Several fundamental headwinds and market dynamics played a role in halting the market’s recovery path:
- Heavyweight Selling in Commercial Banks: Major index drivers, particularly heavy-hitter commercial banks (such as HBL, UBL, and MCB), faced persistent profit-taking and selling pressure during the early sessions, neutralizing positive movements across secondary sectors.
- Macroeconomic Pressures and Inflationary Concerns: Ongoing fiscal concerns—including a broader current account deficit trend, rising central government debt figures, and high utility and commodity prices (such as surging domestic sugar prices)—weighed on investor sentiment.
- Cautious Institutional Participation: Trading volumes and values remained range-bound compared to previous bullish rallies. Total weekly volume hovered around 2.15 billion shares, reflecting a cautious “wait-and-see” approach among institutional players ahead of upcoming corporate earnings announcements and key macroeconomic data releases.
Despite resilient pockets in select exploration and fertilizer scrips, the market remains locked in a consolidation phase as investors look for stronger monetary and fiscal cues to drive a sustained breakout.